The feast-or-famine cycle is an accepted reality of independent work. One month brings a surge of signed contracts, paid retainers, and comfortable liquidity; the next brings delayed client disbursements, quiet project pipelines, and mounting overhead. While most seasoned freelancers learn to adjust their personal spending to match these swings, their credit profiles rarely adapt so easily.
Traditional credit scoring models were engineered around the assumption of predictable corporate employment. Credit bureaus reward steady, automated habits tied to regular biweekly paychecks. For independent contractors, sole proprietors, and creative professionals, mismatched cash flow can quickly distort credit utilization and jeopardize repayment schedules. Managing credit during dry spells requires a deliberate strategy that treats debt servicing as a fixed business cost rather than an afterthought tied to incoming invoices.
The Structural Mismatch Between Invoicing and Credit Scoring
The central vulnerability for self-employed professionals lies in timing. Fixed financial obligations—such as auto loans, mortgages, student loans, and credit card payments—operate on unyielding monthly calendars. Client receivables, conversely, operate on open-ended terms like net-30, net-60, or outright delinquency.
When a major client delays payment by three weeks, a freelancer might rely on credit cards to bridge routine household purchases or upfront business expenses. While this solves immediate liquidity problems, it creates two distinct threats to a credit profile:
First, revolving credit utilization accounts for roughly 30% of a standard credit score. If slow collections force a borrower to use a high percentage of their available credit limit, their credit score can drop dozens of points in a single billing cycle. Lenders view elevated utilization as a sign of financial strain, regardless of whether a five-figure invoice is scheduled to clear next week.
Second, the risk of a missed payment escalates during prolonged dry spells. Because payment history accounts for 35% of a credit score, letting an account lapse past the 30-day mark can inflict severe reputational damage that takes years to rebuild. Avoiding these outcomes requires decoupling your everyday debt management from the irregular timing of your client payments.
Establish a Buffer Fund and Pay Yourself a Fixed Salary
The most effective safeguard against credit degradation is eliminating the direct pipeline between your business bank account and your personal wallet. When freelance income flows straight into personal checking, your ability to pay bills remains hostage to recent invoice activity.
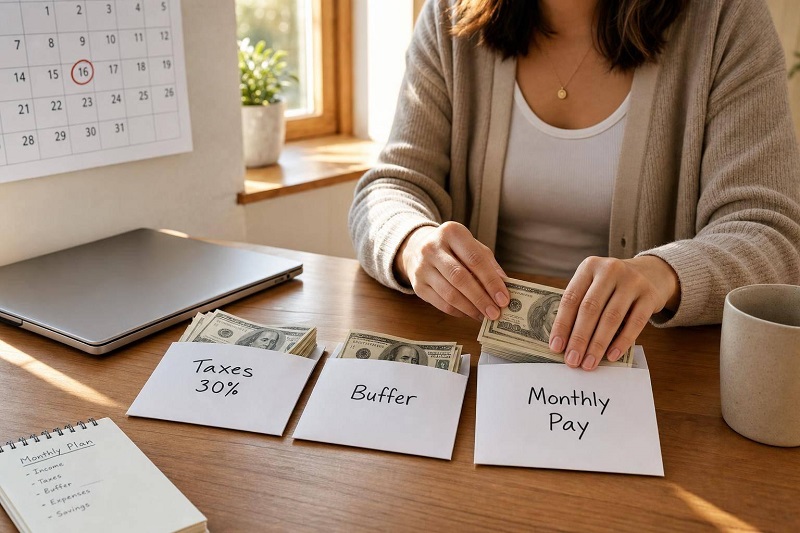
Create an operating buffer by establishing a dedicated business checking account where all client payments land. From that business account, pay yourself a predictable, conservative monthly salary transferred to your personal account on the same day each month.
Base this baseline salary on your historical low-earning months rather than your peak revenue periods. During high-income months, the surplus revenue remains parked in the business account, building a reserve. When dry spells occur, the business reserve absorbs the dip, allowing your personal salary to transfer uninterrupted. Your personal debts, loan installments, and monthly credit balances continue to be settled on schedule without requiring sudden financial compromises.
Master the Difference Between Statement Dates and Due Dates
Credit bureaus do not track how quickly you pay off a balance after an invoice clears; they only see the balance reported by your card issuer on your statement closing date.
Many freelancers assume that paying off their balance in full by the official due date protects their score. However, card issuers report your balance to Equifax, Experian, and TransUnion on the statement closing date, which usually falls 20 to 25 days before the payment due date. If you charge $4,000 in project expenses on a card with a $5,000 limit, a 80% utilization rate is reported to the credit bureaus even if you pay the balance down to zero two weeks later.
To keep your reported utilization low during lean months:
-
Log into your card issuer portal to identify the exact statement closing date, which is distinct from the payment due date.
-
Submit partial payments a few days before the statement closes to keep the reported balance under 10% to 15% of your total limit.
-
Request credit limit increases during peak-earning periods. A higher aggregate limit automatically dilutes your utilization ratio during months when project costs run high.
Separate Business Liabilities from Personal Credit
Freelancers frequently blur the lines between company purchases and household finances. Putting software subscriptions, advertising expenses, subcontractor payments, and client travel on personal credit cards needlessly exposes your personal credit profile to commercial volatility.
Securing a dedicated small-business credit card helps wall off these obligations. Many business cards from major institutions do not report ongoing balances or utilization ratios to consumer credit bureaus, provided the account remains in good standing. This means floating a substantial materials purchase or holding a high balance while awaiting a net-60 corporate check will not depress your personal credit score.
Keep in mind that most business credit card issuers still require a personal guarantee, meaning any serious default or delinquency past 60 to 90 days will eventually reach your personal credit file. Nevertheless, day-to-day balance fluctuations remain isolated from your personal credit records.
Triage Payments Proactively During Severe Cash Crunches
If a market contraction or widespread client payment delays push your cash reserves to the edge, how you triage remaining funds determines whether your credit profile survives intact.
Protect Your Minimums Above All Else
When cash is scarce, the urge to wipe out an entire balance on one card can leave you short on another. Credit scoring algorithms penalize a missed payment far more aggressively than an elevated balance. Distribute available funds so that every open account receives at least its minimum payment due before directing surplus capital anywhere else. Automate minimum payments across all cards using your baseline checking account to guarantee that absentmindedness or stress never leads to an accidental 30-day delinquency.
Contact Issuers Before You Fall Behind
If an unpaid invoice genuinely prevents you from covering a minimum payment, reach out to the creditor before the due date passes. Major credit card companies maintain hardship programs designed to reduce interest rates, waive late fees, or temporarily defer minimum requirements for accounts experiencing short-term disruption. Creditors are far more willing to offer flexible terms to a borrower who initiates communication before an account goes delinquent than to someone whose payment is already several weeks late.
Build Pre-Approved Liquidity While Times Are Good
The most dangerous time to apply for financing is when you desperately need it. When revenue drops, your debt-to-income ratio worsens, bank statements show lower deposits, and underwriters become hesitant to extend new credit lines.
During profitable quarters, establish a revolving personal or business line of credit. A line of credit provides accessible backup liquidity with no ongoing expense if the balance remains unused. Securing this safety net in advance ensures you have low-cost capital available to manage temporary cash flow gaps, keeping high-interest credit card debt off your balance sheet and protecting your credit score from unnecessary volatility.